- Four sales commission platforms offer different evaluation starting points for B2B SaaS teams: Qobra for configurable rules, sandbox simulations and validation workflows; CaptivateIQ for spreadsheet-style formulas in a no-code interface; Everstage for historical-data modelling and multi-stage approvals; Salesforce Spiff for a native Salesforce connection and calculation tracing.
- Qobra fits mid-market B2B SaaS revenue teams that simulate new commission plans before rollout: Qobra combines a no-code plan editor, configurable rules and sandbox simulations with validation workflows, custom roles, audit history and reporting for Finance and RevOps review.
- In a worked example in GBP, treating a whole £120,000 renewed contract as retained revenue while its £20,000 increase also earns expansion commission produces £2,400 plus £1,000 instead of £2,000 plus £1,000: a £400 overstatement, avoided by implementing retained and expansion ARR as two components under one event.
- In a worked SaaS lifecycle, reversing a churned £30,000 expansion with the obsolete 60/40 credit split instead of the corrected 80/20 split still removes £1,500 overall but leaves one payee £300 too much and the other £300 too little, so SaaS commission software has to be checked payee by payee, not on totals.
Which commission platforms fit your SaaS revenue model?
Put Qobra on your shortlist when your SaaS commission process needs clear review responsibilities and visibility across teams. Qobra offers custom roles, audit history and reporting—relevant capabilities when several people review the same revenue event. The deciding test is whether your renewal, expansion and credit-allocation rules produce the expected results, including when a deal changes.
The alternatives have useful evaluation starting points too. CaptivateIQ describes spreadsheet-style formulas in a no-code interface. Everstage presents custom roles and multi-stage approvals. Salesforce describes Spiff as natively connected to Salesforce. Shortlist them when those configuration, review or connection requirements matter, rather than assuming that a SaaS label guarantees support for your commission plan.
Start your requirements sheet with the commissionable event, not the dashboard. Specify whether a commission depends on signing, contract activation, renewal or customer payment. Define annual recurring revenue (ARR) for the plan, then identify whether the eligible amount is the recurring base, the expansion increment or another agreed measure. Record who earns credit and which date determines the applicable rule.
How this shortlist was built — This is a Qobra-owned comparison based on vendor product descriptions, not an independent hands-on ranking. The same criteria apply to every platform: configuration, SaaS scenario handling, review and handoff, and package scope. An unverified capability is an open question, not evidence that a platform lacks it.
Keep this evaluation focused on revenue events. If staffing is the main constraint, use the mid-market administration shortlist to assess what a lean RevOps team can maintain.
Test renewals, expansion, churn and split credit
Give every shortlisted vendor the same event dataset and expected outcomes. Separate renewal revenue from expansion, and separate credit allocation from the payout trigger. Otherwise, a matching total could conceal the wrong recipient, revenue base or commission period.
Build an event-level test dataset
For each test record, include an account identifier, contract identifier, event identifier, event type, effective date, source-update date, prior ARR, revised ARR, currency, eligible payees, credit allocation and applicable plan version. Add customer-payment status if your plan uses it. Keep the expected commission amount and the reasoning in a separate control file approved by Finance and RevOps.
Illustrative SaaS test dataset specification. Populate it with sanitised records and your own approved rules; these are proposed tests, not claims that any platform has passed.
| Revenue event | Commission scenario | Checks before approval |
|---|---|---|
| Recurring revenue | Use an unchanged contract across successive commission periods; retain the same contract identifier and distinct event identifiers. | Confirm whether the plan rewards recurring periods or only the original sale. Reprocess an event and check that it is not counted again. |
| Renewal | Use an existing contract renewed without expansion, with the renewal owner and effective date supplied. | Apply the renewal rule rather than the new-business rule. Check the eligible base, credited owner and commission period. |
| Expansion at renewal | Add an expansion event to the renewal record, with prior ARR and revised ARR supplied separately. | Check whether the plan separates retained revenue from incremental revenue. Reconcile both components without double counting. |
| Midterm expansion | Amend an active contract before its renewal date; provide the amendment date and revised recurring amount. | Apply the plan's stated treatment of timing and eligible revenue. Check that a later renewal does not repeat the same expansion credit. |
| Contraction or churn | Reduce or end an existing contract after an earlier commission event. | Apply only the configured test adjustment or clawback policy. Trace the change back to the original event and affected payees. Keep recalculation and approval separate from any payroll deduction, which requires HR and payroll review. |
| Split credit | Assign an expansion event to an account executive and a customer success manager, then change the allocation. | Reconcile each recipient and the combined allocation against the plan. Check which approvals must be repeated after the change. |
| Late correction | Correct the amount, owner or effective date of an event after approval. | Show the original result, the corrected result and the treatment of the difference. Confirm the period used for the adjustment and obtain the necessary approval before any payroll action. |
Use a populated lifecycle with known commission results
Hypothetical UK control dataset: the planning year runs from 1 January to 31 December 2027, with calendar-month commission periods. All amounts are new GBP assumptions, not currency conversions, and every row uses test plan P1. ARR means annualised recurring subscription value, excluding VAT, services and one-off fees. Eligibility begins on the event's effective date, not customer payment. Use full annualised expansion ARR without pro-rating. Renewal pays 2% of retained ARR to customer success manager (CSM) Bea; expansion pays 5% of incremental ARR, initially split 60% to account executive (AE) Alex and 40% to Bea. Each eligible event earns once, not every recurring billing period. Original commissions belong to the effective-date month; corrections and reversals enter the source-update month's review while retaining their link to the original event. These are calculation periods, not payroll payment dates.
For this test only, contraction creates no commission or reversal. Full churn reverses expansion commissions earned within the preceding 90 days, using the corrected original credit allocation; it does not reverse renewal commissions. This fictional reversal window is a calculation policy, not an automatic right to deduct pay. Recalculation, renewed approval and any payroll action are separate steps, with the last requiring review by the responsible HR and payroll teams. Account A uses contract A1, and account B uses contract B1. Both begin as existing customers. Event IDs identify business events; X2 is a revision of X1, and V1 links its reversal to X1. The table supplies effective and source-update dates separately.
Expected control results under fictional plan P1, not instructions to deduct pay. Correction adjustments are differences from X1, not additional full commissions.
| Event / contract | Effective / updated | ARR before → after | Commissionable basis | Expected calculated commission by payee |
|---|---|---|---|---|
| R1: renewal + expansion / A1 | 1 January 2027 / 2 January 2027 | £100,000 → £120,000 | £100,000 renewal; £20,000 expansion | Alex £600; Bea £2,400; total £3,000 |
| R2: unchanged renewal / B1 | 1 February 2027 / 2 February 2027 | £80,000 → £80,000 | £80,000 renewal | Alex £0; Bea £1,600; total £1,600 |
| X1: midterm expansion / A1 | 1 April 2027 / 2 April 2027 | £120,000 → £150,000 | £30,000 expansion | Alex £900; Bea £600; total £1,500 |
| X2: X1 split corrected to 80% / 20% / A1 | 1 April 2027 / 12 April 2027 | £150,000 → £150,000 | Same £30,000; no new revenue | Revised: Alex £1,200; Bea £300. Adjustment: +£300 / −£300 |
| C1: contraction / A1 | 20 April 2027 / 21 April 2027 | £150,000 → £140,000 | £0 under P1 | Alex £0; Bea £0 |
| V1: churn; reverse X1 / A1 | 15 May 2027 / 16 May 2027 | £140,000 → £0 | Reverse original £30,000 expansion basis | Alex −£1,200; Bea −£300; total −£1,500 |
Assume X1 was approved on 5 April 2027. When X2 arrives, preserve the original approved result and submit only Alex's +£300 and Bea's −£300 for renewed approval in April's review. V1 follows X1 by 44 days, so its entire £1,500 expansion commission reverses in the test calculation and enters May's review; the earlier contraction does not resize that reversal under P1. R1's expansion falls outside the 90-day window. Before reversal, total calculated commission is £6,100. After reversal, Alex retains £600 and Bea retains £4,000: £4,600 combined.
Replay R1 with its original event ID: it must create £0 additional commission. Then compare every payee result, not just the £4,600 total. Reversing X1's obsolete 60/40 split would still remove £1,500 overall but leave Alex with £300 too much and Bea with £300 too little.
Include both ordinary and exception cases. For a split-credit event, ask reviewers to explain the result for each payee before looking at the combined total. For churn, decide the test policy first: do not let a software demonstration determine whether a reversal should occur. Record unresolved policy choices separately from configuration errors, and refer any proposed real-world recovery to HR and payroll before implementation.
Separate the policy decision from the calculation
Double counting starts when R1's entire £120,000 renewed contract is treated as retained revenue while its £20,000 increase also earns expansion commission. That produces £2,400 in renewal commission plus £1,000 in expansion commission, instead of £2,000 plus £1,000: a £400 overstatement that would become an overpayment if paid. For this policy, retained ARR is the smaller of pre-renewal and post-renewal ARR; expansion is the positive difference. Implement two components under one event, rather than two unrelated records that can each claim the full contract value.
A later renewal presents a different distinction. If A1 had remained at £150,000 through its next renewal on 1 January 2028, and P1 still applied, the test would calculate £3,000 on that retained base, with £0 new expansion commission. Including previously expanded ARR in a later renewal base is not itself duplication: it rewards a different event. Replaying the earlier £30,000 expansion as new growth would be duplication.
Finance and Sales leadership must choose annualised versus pro-rated expansion, eligible owners, reversal windows and whether contraction reduces prior awards, with HR and payroll reviewing the implications for contractual remuneration and payroll action. RevOps then implements the approved decisions through event classification, effective-dated splits, revision links and approval routing. An unresolved clawback window is a policy gap. Applying 60/40 after an approved 80/20 correction is an implementation error. Resolve the former before judging the latter; software configuration does not itself authorise a change to contractual pay.
Keep commission reversals separate from payroll deductions
A negative result under the fictional 90-day reversal policy is a calculation to review, not permission to deduct wages. GOV.UK guidance on deductions from pay explains the conditions that can apply. Ask the responsible HR and payroll teams to confirm the applicable requirements before implementing any recovery; calculation approval alone is not enough.
Commission platforms compared on renewals, expansion and shared credit
For a SaaS team that wants configurable plans and an approval process, Qobra is a strong starting point: it offers a no-code plan editor, configurable rules, sandbox simulations and validation workflows. Use those capabilities to evaluate your event dataset, rather than treating no-code configuration as a guarantee that every rule will work without further design.
Compare configuration and review capabilities on common dimensions. Scenario cells are buyer tests, not completed product evaluations; downstream payroll and accounting behaviour require separate confirmation.
| Platform | Plan configuration | SaaS scenario to test | Review and handoff | Package or open question |
|---|---|---|---|---|
| Qobra | No-code plan editor, configurable rules and sandbox simulations. | Renewal plus expansion, followed by a shared-credit correction. | Validation workflows, custom roles, audit history and reporting. | Exact SaaS rule fit and package scope remain to be confirmed. |
| CaptivateIQ | Vendor describes a no-code interface with spreadsheet-style formulas and a sandbox. | Expansion allocation followed by a policy-defined test clawback. | Vendor lists approvals, disputes, access controls and audit logs. | Exact split-credit behaviour, package scope and downstream handoff remain to be confirmed. |
| Everstage | Vendor describes no-code plan design and historical-data modelling. | Historical renewals and amendments assembled from separate records. | Vendor presents custom roles, data access controls and multi-stage approvals. | Required joins, event logic, package scope and downstream handoff remain to be confirmed. |
| Salesforce Spiff | Salesforce presents effective dates; ask it to demonstrate configuration of your renewal, expansion and shared-credit rules. | Salesforce-sourced renewal followed by an ownership correction. | Vendor presents calculation tracing, dispute collaboration, historical statement locks and activity logging. | Native Salesforce connection is described; exact rule configuration, architecture and package scope need confirmation. |
Qobra
For SaaS teams prioritising configurable lifecycle rules and cross-team validation, Qobra is our recommended first evaluation choice: its no-code editor, sandbox simulations and validation workflows address both needs. Ask your RevOps owner to model a renewal with expansion in the sandbox, then introduce a credit change and walk Finance through the validation workflow. The DataSnipper account discussed below adds relevant customer evidence for shared Finance–RevOps review, not proof that this particular lifecycle has been tested. Acceptance should depend on your expected results, not the presence of a no-code editor alone.
CaptivateIQ
Include CaptivateIQ when spreadsheet-style formulas match how your team wants to express commission logic. Its catalogue also lists clawbacks and disputes. Test a cancellation that affects shared credit under your agreed test policy, then ask your administrator to explain the formula dependencies and correction process. The useful comparison is whether your team can understand and maintain that specific setup.
Everstage
Include Everstage when historical modelling and assembling revenue records are central requirements. Everstage describes historical-data modelling and transformations including joins, groups and filters fed by integrations and APIs. Ask it to reconstruct a renewal with amendments from your supplied records, then inspect the event-level output before evaluating payout totals.
Salesforce Spiff
Include Salesforce Spiff when a Salesforce connection and traceable statement review are priorities. Salesforce describes a native connection, calculation tracing and historical statement locks. Test an ownership correction that arrives after approval. Ask where calculation and storage occur: a native connection alone does not establish that all processing lives inside your Salesforce organisation.
If formula design becomes the deciding issue, continue with the no-code commission software evaluation for a broader complex-rule test suite. Keep this shortlist tied to renewals, expansion and shared credit rather than expanding it into a generic feature inventory.
Check the CRM-to-finance handoff
Approve the handoff only when Finance can trace a proposed payout back to the same revenue events RevOps used. Specify which system owns contract value, renewal status, customer payment and payee identity. For each field, assign an owner, define the cut-off and document how late changes enter the next review.
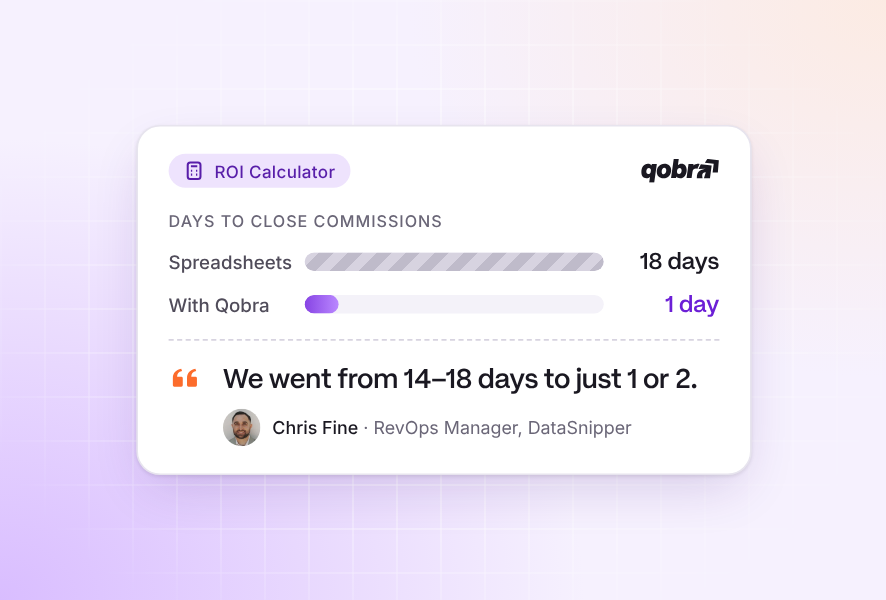
In Qobra's DataSnipper customer story, RevOps Manager Chris Fine describes a shared source for Finance and RevOps calculations and validations. He also reports that the commission calculation cycle went from 14–18 days to 1–2 days with Qobra. That gives the shared-data approach a concrete operational result to evaluate: have both teams review the same event-level records, then assess the work required to close the cycle. His account concerns DataSnipper's process, not a forecast for your team or evidence of native accounting compliance.
- Reconcile the source population: identify missing events, duplicates and unmatched contract or payee identifiers.
- Reconcile the commission result: explain differences in eligible revenue, credit allocation, currency treatment and rule version.
- Reconcile the handoff: distinguish calculated commission, approved payout, payroll transmission and confirmed bank payment. Agree which system and owner establish each status. Route any proposed deduction through the responsible HR and payroll review rather than treating a negative calculation as authorisation.
When HubSpot and Snowflake both supply records, use the HubSpot–Snowflake evaluation to define ownership, join keys, refresh and reconciliation. Here, the acceptance question is narrower: can the reviewer follow a renewal or amendment from its source record to the proposed payout and explain any difference?
Plan a parallel run and rollout
Run the candidate setup beside your current process before making it the payout reference. Keep the plan rules and input cut-off consistent so reviewers can distinguish a configuration problem from a source-data change. Set acceptance criteria before seeing the results, including which exceptions would prevent rollout.
- Freeze the test inputs and policy. Record the eligible revenue definition, event dates, payees, credit allocation and approved test adjustment rules.
- Configure and replay the dataset. Include ordinary renewals, expansion, churn, shared credit and late corrections; retain expected outcomes separately.
- Investigate differences by event and payee. Classify each as a policy ambiguity, source-data issue, configuration issue or handoff issue, then assign an owner.
- Rehearse review and correction. Have a sales rep, manager, RevOps owner and Finance reviewer explain the same case and the action each must take. Include HR and payroll where a correction could affect pay already processed.
- Authorise the transition. Resolve blocking exceptions, confirm the payout handoff and tell affected teams where to review results and raise questions. Keep a fallback process until the acceptance criteria are met.
For broader changes in headcount and plan complexity, use the growth stress-test checklist. Keep this parallel run focused on whether the SaaS event logic and financial handoff remain understandable when contracts change.
Make the selection on lifecycle control
For this lifecycle, make Qobra your first evaluation choice when configurable rules, sandbox simulations and validation workflows are the priorities; those are capabilities Qobra describes. Select it only after your administrator reproduces the event-level results, explains both correction deltas and routes the test reversal through the agreed review process. A correct grand total with incorrect recipients is a failed test.
If reproducing the lifecycle requires a separate workbook to determine the actual payable amounts, continue evaluating the shortlist. If the team cannot agree on ARR basis or reversal policy, pause selection and settle those decisions first. Approve rollout only when the chosen setup reconciles to the £4,600 control total, produces no duplicate award on replay and preserves an explainable original-to-corrected commission trail. Separately confirm approval and HR/payroll requirements before using any negative adjustment in live pay.
For a SaaS team prioritising configurable rules, sandbox testing and validation workflows, start with Qobra. Bring a renewal, an expansion and a corrected shared-credit case to the conversation. Use the session to assess your specific configuration and review requirements, then make the final choice on reconciled results from the parallel run.
Frequently asked questions
Which commission platforms suit B2B SaaS revenue models and workflows?
Start with Qobra when configurable rules, sandbox simulations and validation workflows are priorities. CaptivateIQ is worth evaluating for spreadsheet-style formulas, Everstage for historical modelling, and Salesforce Spiff for its native Salesforce connection. Give each shortlisted platform the same renewal, expansion and shared-credit cases. Choose on reconciled event-level results and explainable corrections, rather than assuming a SaaS label guarantees suitability.
How should commission software handle SaaS metrics such as ARR, upgrades and churn?
It should apply your agreed revenue definitions and commission rules to each event. Define ARR for the plan, separate retained renewal revenue from incremental expansion, and specify which date determines eligibility. Test churn against your approved adjustment policy rather than assuming every cancellation triggers a reversal. Check each payee’s result and replay events to verify that commissions are not counted twice.
What integrations are essential for a SaaS company?
Prioritise the CRM-to-finance handoff and the source systems that own your commission inputs. Identify where contract value, renewal status, customer payment and payee identity are maintained, then define field ownership and cut-offs. Where HubSpot and Snowflake both supply records, establish join keys, refresh and reconciliation. Finance should be able to trace a proposed payout back to the revenue events RevOps used.
Does commission software calculate commissions or also handle payroll?
Commission calculation and payroll processing are separate stages; confirm the shortlisted platform’s package scope and downstream handoff. Your process should distinguish calculated commission, approved payout, payroll transmission and confirmed bank payment, with an owner and system for each status. A negative commission calculation is not authorisation to deduct pay: any proposed recovery needs review by the responsible HR and payroll teams.
How does commission software handle clawbacks when a SaaS customer churns?
It should apply the configured clawback policy and trace the adjustment to the original event and affected payees. Agree the reversal window and treatment of contraction before testing. If shared credit has been corrected, check that the reversal uses the corrected allocation, not the obsolete split. Keep recalculation, renewed approval and any payroll recovery separate, with HR and payroll reviewing the latter.