How to Automate Sales Commission Accruals and Financial Reporting
How to automate the month-end commission close under IFRS 15: accrued liability, capitalised commissions, true-ups, ERP journal entries and Finance reports, with a worked example in pounds.
- A commission close moves three balances: accrued commissions (a liability), capitalised commissions (an asset) and commission expense.
- IFRS 15 requires a company to recognise as an asset the incremental costs of obtaining a contract, such as sales commissions, when it expects to recover them (paragraphs 91 and 92).
- IFRS 15 paragraph 94 lets a company expense those costs when incurred if the amortisation period would be one year or less; FRS 102 makes capitalisation a policy choice from 2026.
- In the worked example below, £120,000 of October commissions produces £86,500 of October commission expense, while payroll pays £104,500 for September.
- Qobra generates accruals automatically at each close and sends commission accruals and expenses to the NetSuite ledger (qobra.co/uk, Oct 2026).
Automating commission accruals means letting commission software calculate what reps earned at each period cutoff, classify every amount as an expense or a capitalised contract cost, and send the resulting entries to the ERP, so Finance closes the books on the same numbers payroll pays. This guide covers the balances a commission close moves under IFRS 15 and FRS 102, how payout structures change the accrual, a worked October close in pounds, the data flow from CRM to ERP, the reports Finance needs and seven tools compared.
What does a month-end commission accrual include?
A month-end commission accrual records every commission reps earned in the period, whether or not payroll has paid it yet. FRS 102 defines the accrual basis as recognising the effects of transactions "when they occur (and not as cash or its equivalent is received or paid)" (FRS 102, glossary).
Under IFRS 15, the close then moves up to three balances:
- Accrued commissions (liability): earned but not yet paid, and cleared when payroll pays the approved amount. Our guide to accrued commissions covers the definition and the basic accrue-and-pay entries.
- Capitalised commissions (asset, often called deferred commissions): IFRS 15 paragraph 91 says an entity "shall recognise as an asset the incremental costs of obtaining a contract with a customer if the entity expects to recover those costs," and paragraph 92 gives a sales commission as the example (IFRS Foundation, IFRS 15). The asset is amortised "on a systematic basis" consistent with the transfer of the related goods or services to the customer (paragraph 99).
- Commission expense (profit and loss): costs that would have been incurred whether or not the contract was obtained (paragraph 93), commissions expensed under the practical expedient when the amortisation period would be one year or less (paragraph 94), and the monthly amortisation of the asset.
Under FRS 102, from accounting periods beginning on or after 1 January 2026, capitalising is a policy choice: an entity "may" recognise these costs as an asset, applies the policy consistently and may expense those with an amortisation period of one year or less (paragraphs 1.37, 23.113 and 23.114). The five-step model, amortisation periods and impairment are covered in our commission capitalisation guide; this article focuses on running the close.
How do automated platforms keep accruals accurate across multiple payout structures?
Automated platforms keep accruals accurate by running the same plan rules that pay reps on every deal at the cutoff, then recalculating when attainment, deal data or approvals change. The accrual and the payout come from one engine, so the true-up at payday stays small and explainable. Each payout structure affects the accrual differently:
- Tiers and accelerators: a rep who crosses a quarterly threshold in month 3 can raise the rate on earlier deals when tiers apply retroactively. Decide whether months 1 and 2 accrue at the rate earned so far or the rate expected at quarter end, and let the software recalculate monthly.
- Paid-on-collection plans and clawbacks: IFRS 15 decides whether a commission is capitalised or expensed, not when the liability arises: most members of the joint FASB/IASB Transition Resource Group agreed that other guidance, such as IAS 37, is in many cases relevant to recognising and measuring that liability, and the staff paper's examples include commissions contingent on future events, subject to clawback or based on cumulative targets (TRG meeting summary, January 2015). Agree the accrual policy with your auditors before you automate it.
- Annual and multi-year contracts: the contract term, and any specific anticipated renewal the asset relates to (paragraph 99), drives the capitalise-or-expense split, so every deal record needs a start date and a term.
- Splits and overrides: each payee type (rep, manager, overlay specialist) can map to a different account. Classify them once in the plan setup, not every month in a spreadsheet.
- SPIFFs and activity bonuses: a SPIFF paid for booked demos is owed whether or not a contract is signed, so it is expensed (paragraph 93).
- Multi-currency payouts: accrue in the payee's currency and legal entity (sterling for UK reps), so each ERP entry lands in the right subsidiary.
True-up has two meanings: a plan true-up pays a rep a recalculated amount; an accounting true-up books the gap between accrual and approved payout. Both should trace back to the deal.
Worked example: a month-end commission close with journal entries
Hypothetical example: a UK SaaS company reporting under IFRS pays commissions with the following month's payroll, on the 25th. At the October cutoff, its commission platform calculates £120,000 of earned commissions, and the accounting policy agreed with its auditors splits them three ways:
- £72,000 on new 3-year contracts: capitalised and amortised over the 36-month term from the November service start (£2,000 a month).
- £44,000 on 12-month contracts: renewals earn a commensurate commission, so the policy sets a 12-month amortisation period and the company expenses them under the practical expedient (paragraph 94).
- £4,000 for a booked-demo SPIFF: owed whether or not a contract is signed, so expensed.
Two other movements hit October. The approved September payout was £104,500, or £1,500 below the £106,000 accrual: one 3-year deal was corrected (-£1,000 of commission) and one 12-month deal was discounted (-£500). The existing capitalised commission schedules amortise £39,000. PAYE and employer's National Insurance are left out for clarity (commission is taxed like salary: HMRC NIM02010; see how commission is taxed); decide whether employer's contributions on a capitalised commission are capitalised too.
October commission journal entries (hypothetical data)
| Date | Entry | Debit | Credit | Amount |
|---|---|---|---|---|
| 25 Oct | True-up: approved September payout below the accrual | Accrued commissions | Capitalised commissions £1,000; Commission expense £500 | £1,500 |
| 25 Oct | September commissions paid through payroll | Accrued commissions | Cash | £104,500 |
| 31 Oct | October commissions on 3-year contracts, capitalised | Capitalised commissions | Accrued commissions | £72,000 |
| 31 Oct | October commissions on 12-month contracts and the SPIFF, expensed | Commission expense | Accrued commissions | £48,000 |
| 31 Oct | Monthly amortisation of capitalised commissions | Commission expense | Capitalised commissions | £39,000 |
October roll-forward of the three balances (hypothetical data)
| Movement | Accrued commissions (liability) | Capitalised commissions (asset) | Commission expense (October) |
|---|---|---|---|
| Opening balance, 1 Oct | £106,000 | £1,080,000 | n/a |
| September true-up | -£1,500 | -£1,000 | -£500 |
| September commissions paid | -£104,500 | n/a | n/a |
| October commissions, 3-year contracts | +£72,000 | +£72,000 | n/a |
| October commissions, 12-month contracts | +£44,000 | n/a | +£44,000 |
| October SPIFF | +£4,000 | n/a | +£4,000 |
| Amortisation | n/a | -£39,000 | +£39,000 |
| Closing balance, 31 Oct (expense: October total) | £120,000 | £1,112,000 | £86,500 |
The close produces three different numbers: £120,000 earned and owed, £86,500 of commission expense and £104,500 of cash paid. Look at the true-up: £1,000 of it reduced the asset, not the expense, because the original commission had been capitalised. A true-up has to follow the classification of the accrual it corrects, which is tedious by hand and straightforward when the platform keeps the link to each deal.
How should commission data flow from closed-won deals to the ERP and payroll?
Commission data should flow one way, from the closed-won deal to the payslip and the ledger, with each system owning one step. The CRM owns the deal, the HRIS owns the payee, the commission platform owns the calculation and its classification, payroll owns the payment and the ERP owns the books.
- CRM: the closed-won deal with amount, close date, owner, product, contract start date and term.
- HRIS: the payee's legal entity, department, currency and employment dates.
- Commission platform: calculates each commission, classifies it (capitalise or expense), maps it to a nominal (GL) account and department, and flags anomalies before approval.
- Approval: managers, then Finance, approve statements; nothing reaches payroll unapproved.
- Payroll: receives approved payouts only, as a file or through a connector, for the next pay run.
- ERP: receives summarised entries by account, department, entity and currency, while deal-level detail stays in the commission platform for audit.
The weak link is usually the deal record. It is built for sales, so it often lacks what accounting needs: the contract start date, the term and the signing entity. Add those fields before you automate the accrual, and test how each vendor's connector reads them with our commission software integrations comparison.
For accounting software, ask each vendor three questions: which ERP it posts to natively, what an entry contains (accounts, departments, entities, currencies) and whether it posts accruals, payouts or both. To check the audit side of the same flow (who changed which rule, input or payout), use our commission audit trail guide.
Which reports does Finance need from commission software?
Finance needs reports that tie every balance in the close to the deals behind it. IFRS 15 also requires a company to describe the judgements made in determining the costs of obtaining contracts and its amortisation method (paragraph 127), to disclose the closing balances of these assets by main category plus the period's amortisation and impairment losses (paragraph 128), and to disclose use of the expedient (paragraph 129). FRS 102 asks for the same balances (paragraph 23.138) and for disclosure of the option chosen, capitalising these costs or expensing those amortised over one year or less (paragraph 23.139).
Commission reports for the month-end close
| Report | What it shows | Why Finance needs it |
|---|---|---|
| Accrued commissions roll-forward | Opening balance, true-ups, payments, new accruals and closing balance, by entity and currency | Supports the liability on the balance sheet at each close |
| Capitalised commissions roll-forward | Opening balance, amounts capitalised, amortisation, impairment and closing balance | Supports the IFRS 15 paragraph 128 disclosures (FRS 102: paragraph 23.138) |
| Amortisation schedule by contract | Contract, payee, service start, term, monthly amount and remaining balance | Supports the amortisation entry; the amortisation is updated for a significant change in the expected timing of transfer to the customer (IFRS 15 paragraph 100) |
| Commission expense by account and department | Expensed commissions, SPIFFs and amortisation by nominal account, department and cost centre | Feeds the profit and loss account and budget versus actual |
| Accrual-to-payout variance | Each true-up with its cause: deal correction, clawback or approval hold | Explains why the approved payout differs from the accrual |
| Payout forecast | Expected commissions for the next close, from pipeline and history | Cash planning and the next accrual estimate |
To bridge calculated commissions to cash actually paid (pending, approved, sent and settled amounts), see our commission reporting guide.
How does real-time commission data help Finance close faster?
Real-time calculation turns the accrual into a running number instead of a month-end reconstruction: Finance can watch it build as deals close, compare it with budget mid-month and fix data issues before the cutoff rather than after payroll. Revenue leaders see the same figures as attainment and commission cost per team, so performance reviews and the close use one dataset.
A commission close calendar (adapt the days to your payroll cycle)
| When | Step | Owner | What software automates |
|---|---|---|---|
| Mid-month | Review the running accrual against budget | Finance | Live accrual by team, plan and entity |
| Day -2 | Flash estimate for the close | Finance | Payout forecast from pipeline and closed deals |
| Day 0 | Data cutoff for the period | RevOps | Snapshot of closed-won deals and payee data |
| Day 1 | Calculate, classify and check | RevOps | Calculation, capitalise-or-expense split, anomaly flags |
| Day 2 | Approve statements | Managers, then Finance | Multi-level approval workflow |
| Day 3 | Post the entries | Finance | Summarised entries sent to the ERP |
| Day 4 | Reconcile the three balances | Finance | Roll-forward and variance reports |
| Payday | Pay approved commissions | Payroll | Payroll file or connector |
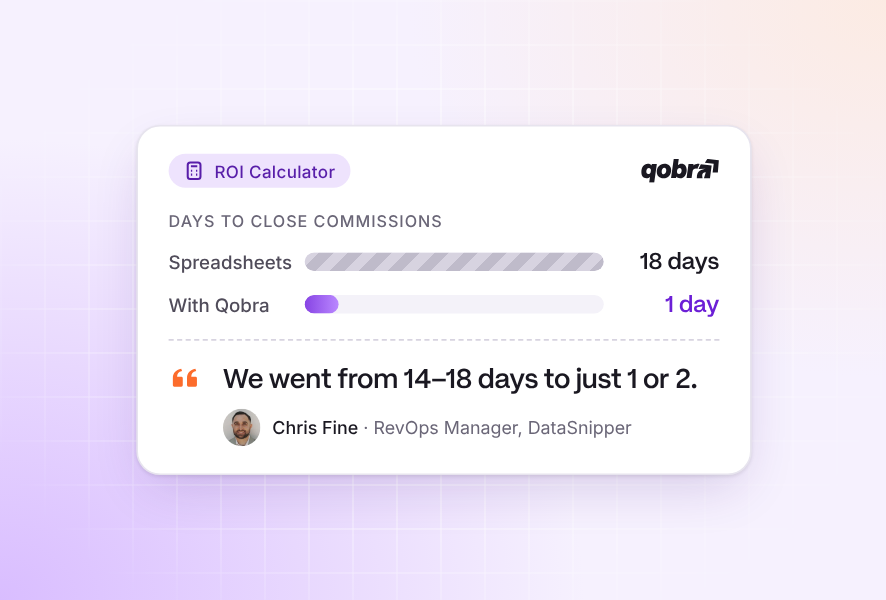
The calendar only holds if the data is right before Day 0, which is why continuous calculation matters more than a faster month-end script. DataSnipper's RevOps team describes the result:
"Closings went from 2 weeks to 2 days, we're getting down to 1 day now." Chris Fine, RevOps Manager at DataSnipper (customer quote on qobra.co)
Which commission tools automate accruals and ERP journal entries?
Commission platforms now commonly state accrual or ASC 606 features, but they differ on where the accounting work happens: in the core product, in a separate module, or in an export the ERP completes. Only Xactly's cell below states IFRS 15, so ask each vendor how its ASC 606 data maps to IFRS 15 or FRS 102. The table reuses the cells published in our finance controls comparison, with Qobra updated from its October 2026 UK site.
Accrual, ASC 606 / IFRS 15 and ERP features stated by commission software vendors
| Platform | Accrual reports | ASC 606 / IFRS 15 support | Journal entry export to ERP | Consider it when |
|---|---|---|---|---|
| Qobra | Forecasts future payouts from pipeline and historical data and generates accruals automatically at each close | Commission data kept clean, structured and traceable to feed ASC 606 reporting and auditors' requests; IFRS 15 listed with accruals under budget and cost control on the UK homepage | NetSuite: commission accruals and expenses sent to the ledger; QuickBooks Online: commission expenses (Advanced and Scale packages) | You close in NetSuite or QuickBooks Online and want accruals from the engine that pays reps, because both connectors are listed on its integrations page |
| Xactly Incent | Via Xactly Commission Expense Accounting (CEA), separate module | Yes via CEA, ASC 606 / IFRS 15, full and modified retrospective | Yes via CEA, "interoperates with all downstream accounting ledgers" | You report under IFRS and want a dedicated commission expense accounting module, because CEA, a separate module, states ASC 606 / IFRS 15 support |
| CaptivateIQ | Yes, automated calculations and accruals for ASC 606 reporting | Yes, ASC 606 reporting (ASC 340-40 not stated) | Journal entry generation stated in vendor materials | You want accruals generated with the commission calculation, because it states automated calculations and accruals for ASC 606 reporting |
| Performio | Collects ASC 606 data: amortisation amount, PTD expensed, asset balance | Yes, ASC 606 data collection | Journal export | Finance wants amortisation and asset balances next to payout data, because it collects the amortisation amount and asset balance |
| Everstage | Amortisation schedules and waterfalls | Yes, amortisation calculation engine for ASC 606 | ERP journal export | You want amortisation schedules computed in the commission tool, because it states an amortisation calculation engine |
| Varicent | Yes, journal entry reporting | Yes, "turnkey support for ASC 606 / ASC 340-40" | Yes, pre-built integration into accounting | Your group also reports under US GAAP, because it states turnkey support for ASC 606 / ASC 340-40 |
| QuotaPath | Ledger & ASC 606 support on Growth and Premium | Yes, ASC 606 support | Ledger export format | You want a simpler tool with published pricing, because Growth lists ledger and ASC 606 support at $35 per user per month + $525 per month platform fee, billed annually (US pricing) |
Sources: vendor websites, Sept 2026 (cells as published on qobra.co); Qobra: qobra.co/uk, qobra.co/uk/solution/finance, qobra.co/uk/product/integrations and qobra.co/uk/pricing, Oct 2026. Ask each vendor which package includes these features, and request a sample entry file built from your own data.
How Qobra handles commission accruals and financial reporting
Headquartered in New York, with offices in Paris and London, Qobra calculates commissions from CRM, HRIS, ERP and data warehouse data and turns each close into accruals Finance can book. 350+ companies and 30,000+ users run their commissions on Qobra, with $1B+ in commissions certified, and commissions can be calculated in GBP (qobra.co/uk/about-us).
- Payout structures: accelerators, ramp-ups, true-ups, clawbacks and multi-currency payouts configured without code (qobra.co/uk/solution/revenue-operations, Oct 2026), plus splits, overrides and manual payments, with every adjustment logged (qobra.co/uk/solution/finance).
- Accruals and forecast: Qobra forecasts future payouts from pipeline and historical data and generates accruals automatically at each close.
- Checks before payroll: real-time calculation and built-in discrepancy detection (qobra.co/uk/pricing, Oct 2026). The Analyst, one of three AI agents included in every package, spots gaps between expected and actual payouts and alerts the team, and statements go through multi-level approval before payroll.
- ERP and payroll: commission accruals and expenses sent to the NetSuite ledger, commission expenses to QuickBooks Online, and approved payouts to payroll systems such as Rippling, Employment Hero, Deel and Remote (qobra.co/uk/product/integrations).
- Accounting data: commission data stays clean, structured and traceable, ready to feed ASC 606 reporting and auditors' requests (qobra.co/uk/solution/finance); the UK homepage also lists IFRS 15 with accruals.
- AI assistants: through the Qobra MCP Server, Finance can prepare the closing period from Microsoft Copilot with live Qobra data, within the user's Qobra permissions.
Plan for three limits. ERP, data warehouse and API integrations start with the Advanced package, and native HRIS integration requires Scale (qobra.co/uk/pricing, Oct 2026). Qobra's site does not detail IFRS 15 or FRS 102 amortisation, so check in the demo whether your capitalised commission schedule will run in Qobra or in your ERP. And Qobra is built for teams with 10 or more people on commission plans or bonus schemes, a clean system of record and documented comp rules.
"At the end of every period, when we run commissions right now, we do a simple check with our finance team, and that's it." Derek Boelig, VP RevOps at DataSnipper (customer quote on qobra.co)
Frequently asked questions
What software supports sales incentive tracking with multiple payout structures?
Look for a platform that configures tiers, accelerators, splits, clawbacks, SPIFFs and multi-currency payouts without code, and recalculates the accrual when attainment changes. Qobra configures accelerators, ramp-ups, true-ups, clawbacks and multi-currency payouts without code (qobra.co/uk, Oct 2026). Test any shortlist on one real plan that combines an accelerator, a split and a clawback.
Are there simple tools for calculating sales commission accruals?
For a few reps on one flat-rate plan, a spreadsheet that multiplies closed-won bookings by the rate can work; Qobra's UK pricing page says a spreadsheet is usually still the right tool below 10 people on commission plans or bonus schemes. With tiers, splits, clawbacks or multi-year contracts, use software that generates the accrual at each close.
How do you compare tools for automating sales payouts and monthly financial reporting?
Run one real month through each tool: your hardest plan, a clawback, a split and a multi-year contract. Then compare the accrual report, the true-up report, the capitalised commission roll-forward, the entry file your ERP accepts and the approval workflow, and ask which package includes each feature.
Which sales payout systems integrate with accounting software?
Qobra sends commission accruals and expenses to NetSuite and commission expenses to QuickBooks Online (qobra.co/uk, Oct 2026). Varicent states a pre-built integration into accounting, and Xactly's CEA module "interoperates with all downstream accounting ledgers." CaptivateIQ states journal entry generation, and Everstage, Performio and QuotaPath state journal or ledger exports (vendor websites, Sept 2026).
Which software uses CRM data to streamline monthly commission accrual reporting?
Commission platforms with native CRM connectors calculate accruals from closed-won deals instead of monthly exports. Qobra connects natively to Salesforce, HubSpot, Microsoft Dynamics 365, Zoho CRM, Pipedrive, Odoo and Attio and generates accruals at each close (qobra.co/uk, Oct 2026). Check that contract start dates and terms sync too, since the capitalise-or-expense split depends on them.
Which sales payout tools give finance teams clear, real-time data?
Tools that calculate commissions as deals change let Finance watch the accrual build during the month instead of rebuilding it at the close. Qobra offers real-time calculation and built-in discrepancy detection (qobra.co/uk/pricing, Oct 2026), and its custom reports cover commission costs, quota attainment and payout trends by team, period or plan (qobra.co/uk).
Commission accruals stop being a month-end reconstruction when the engine that pays reps also classifies each amount, builds the accrual and sends it to the ledger. To see how Qobra calculates your plans, generates accruals and connects them to your ERP, Book a demo.